What it does
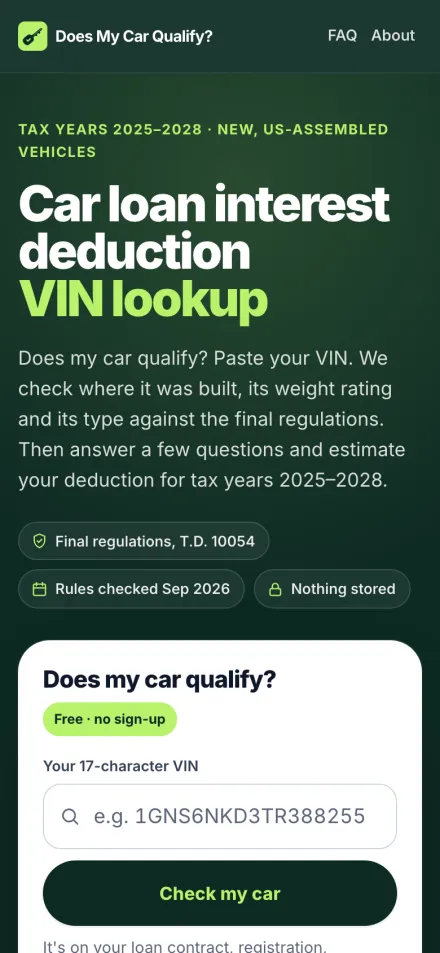
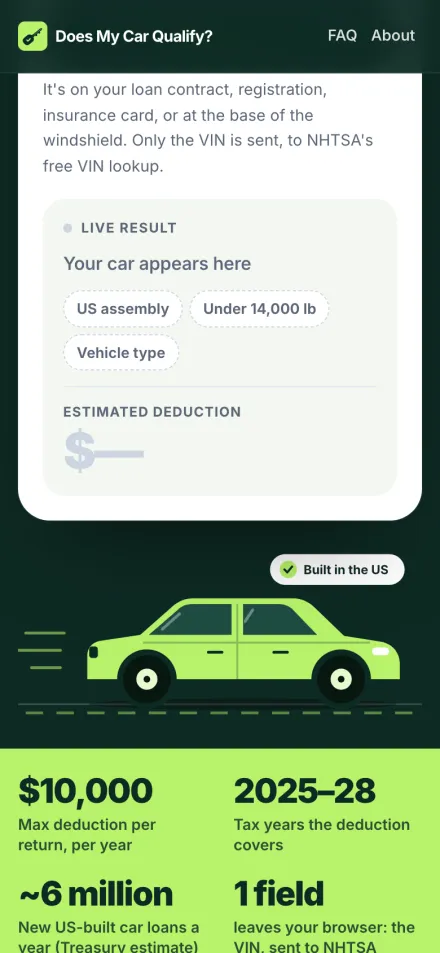
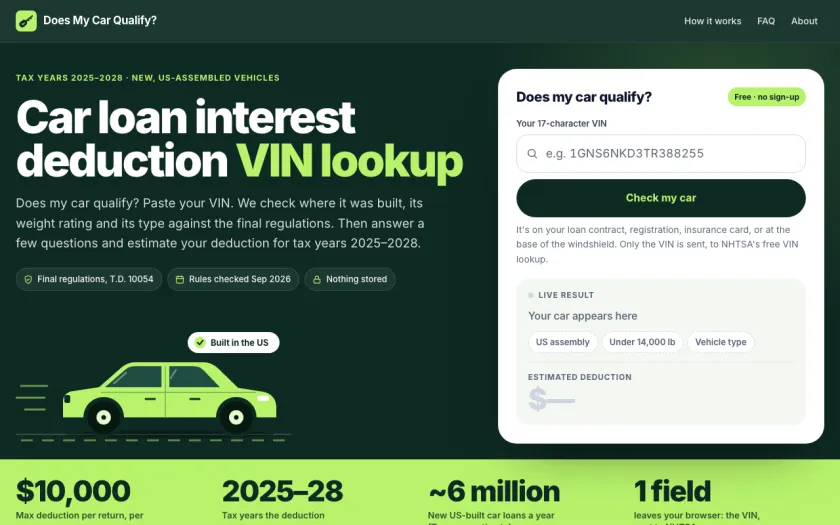
This is a free calculator for the new car loan interest tax deduction, which starts with tax year 2025. You paste in your car's 17 character VIN. The tool then checks three vehicle details the deduction rule looks at: the assembly plant, the weight rating, and the vehicle type.
After the vehicle check, you answer a short set of yes or no questions about your loan, since the rest of the rule cannot be read from a VIN. The tool then estimates your deduction, including the income based phase out and the rules for refinanced loans.
Screenshots
Features
- VIN based vehicle checkPaste in your VIN and the tool reads back the plant of manufacture, the gross vehicle weight rating, and the vehicle type, then checks each one against the deduction rules.
- Handles the exactly-14,000-lb edge caseSome heavy pickups are rated at exactly 14,000 lb, which fails the rule, but the VIN lookup only returns a weight range. When your truck falls in that range, the tool asks for the exact figure from your door jamb label.
- Manual entry fallbackIf the VIN lookup is down, or your vehicle has no window sticker, such as a motorcycle or a heavier pickup or van, you can skip it. Type in the vehicle type, the assembly plant, and the weight rating by hand instead.
- Deduction calculatorOnce the vehicle passes, the tool applies the $10,000 yearly cap, the income based phase out, and the rules for refinanced loans and partial business use to estimate your deduction.
- Section 179 answer for business vehiclesThe tool also answers whether a vehicle counts as a heavy SUV or pickup for Section 179 business depreciation, which uses a different weight cutoff.
- Worked example and listed sourcesThe page works through a full example step by step, and lists the Treasury regulation and IRS forms behind the rules.
How it works
When you press the check button, your browser sends only the VIN to NHTSA's free vehicle lookup, with no referrer attached. Nothing else about your loan or your income is sent anywhere. The tool reads three fields back from that lookup and checks them against the deduction rule.
From there, the rest runs in your browser. You answer the loan questions and type in numbers like your interest paid and your income, and the tool runs the cap and phase out math on your device.
Known limits
- This is an estimate, not tax advice, and the tool is not affiliated with the IRS, the Treasury, or NHTSA. The IRS, or your own tax preparer working through your full return, gives the final answer.
- The VIN cannot show whether the car was new to you, how your loan is secured, or how much you use the car for business. You answer those parts yourself.
- The interest estimate assumes a standard monthly payment schedule. Use the figure from your Form 1098-VLI once you have it, since lenders calculate interest daily.
- The deduction covers only loans taken out after December 31, 2024, for tax years 2025 through 2028, on new US-built vehicles under 14,000 lb.
Privacy
The only piece of information that leaves your browser is the VIN, sent directly to NHTSA's vehicle lookup with no referrer attached. It is never sent to the site's own servers.
Your loan answers, your interest figures, and your income stay in your browser. There is no account and no server side database. As of this writing the site doesn't set cookies or run any analytics, though it plans to add Google AdSense ads later, which will update this page.
Read the full Car Loan Deduction Checker privacy policy
Questions
Does the first letter of my VIN prove my car was built in the US?
No. That character only shows the manufacturer's regional code. The tool checks the actual assembly plant field instead, since the same model can be built in more than one country.
My truck is rated at exactly 14,000 lb. Does it qualify?
No. The rule requires a gross vehicle weight rating under 14,000 lb, so a truck rated at exactly that weight does not pass.
Can I use this deduction if I take the standard deduction instead of itemizing?
Yes. You can claim it either way, itemizing or taking the standard deduction; the two are not connected.
Does a leased car or a lease buyout qualify?
No. Lease payments are not loan interest, and buying out a lease does not qualify either, because the leasing company was the vehicle's first owner.
Can one vehicle qualify for both Section 179 and this car loan deduction?
No. One vehicle can't use both at once: this deduction needs mostly personal use, over 50%, while Section 179 needs mostly business use instead.